Member Content
Ubiquity Begets Ubiquity: Why the Future of Messaging Requires Both RCS and SMS
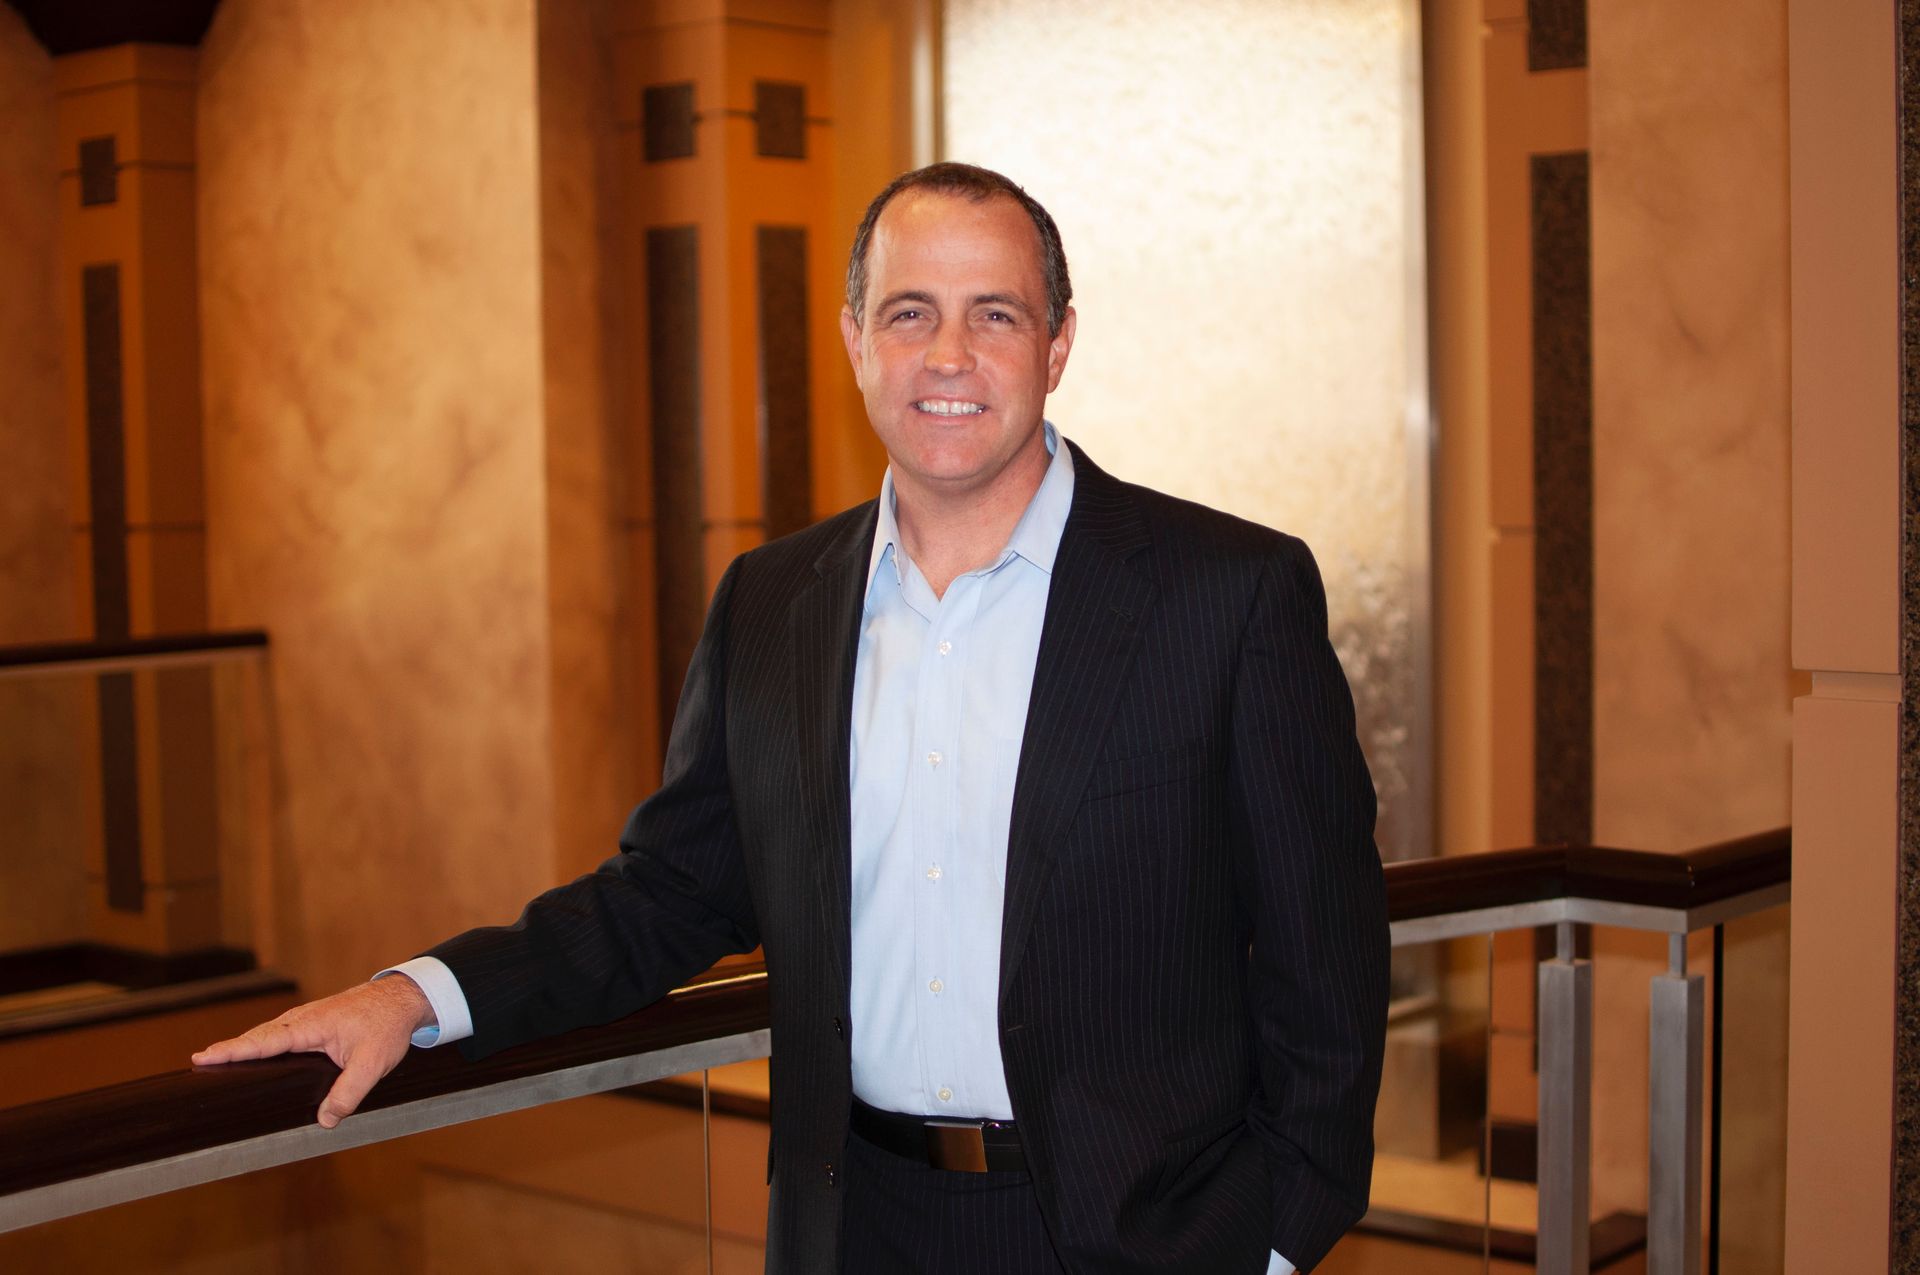
By Jim Dwyer III, Senior Vice President, Corporate Development
Interop Technologies
Few communications technologies achieve true ubiquity. SMS did.
Its enduring value comes from a straightforward proposition: nearly every mobile user can be reached, regardless of device, operating system or network. That reach has made SMS an essential communications channel for consumers, enterprises and mobile operators alike.
RCS represents the next evolution of that experience. It gives businesses the ability to communicate through verified sender profiles, rich media, interactive content, suggested actions and two-way conversations. However, the long-term success of RCS will depend on more than the capabilities it offers.
Features may generate interest, but scale changes markets.
For RCS to influence how businesses invest in mobile messaging—and how consumers engage with those messages—it must become consistently available across the mobile ecosystem. The industry must, in effect, fight ubiquity with ubiquity.
Scale Is a Strategic Requirement
RCS adoption is not simply a technology deployment decision. It is a market-development opportunity that depends on participation across operators, subscribers, devices and platforms.
Every operator that enables RCS expands the addressable audience for RCS Business Messaging. As that audience grows, brands gain greater confidence that their campaigns can achieve meaningful reach. That confidence encourages additional enterprise investment, supports more sophisticated use cases and strengthens the revenue opportunity for participating operators.
In late 2023, Google reported more than one billion monthly active users with RCS enabled in Google Messages. That scale is already taking shape. Infobip recently reported 169.3% growth in RCS for Business traffic from the first half of 2025 to the first half of 2026. In the United States, RCS interactions among its customers increased 1,298.8% year over year, with more than 1.5 billion RCS messages delivered in the country by late July 2026. These results indicate that brands are moving beyond experimentation and beginning to deploy RCS at meaningful scale.
Yet gaps in subscriber availability still introduce complexity for brands and aggregators, reduce campaign reach and slow broader adoption. Operators waiting for the RCS market to achieve full scale before participating may therefore delay the scale they are waiting to see.
Ubiquity is not a condition that will exist before operators act. It will be the result of operators acting.
Turning Capability Into Commercial Value
The strategic value of RCS becomes clearer when viewed through practical use cases.
A retailer can present products through branded rich cards, provide personalized recommendations and allow customers to complete an action directly from the the native messaging app. Financial institutions can send verified fraud alerts and give customers an immediate way to confirm a transaction or contact support. Airlines and hotels can combine confirmations, itinerary updates, check-in functions and upgrade offers within a continuous messaging experience.
Healthcare providers can streamline appointment reminders and prescription notifications, while utilities can deliver outage information, billing notices and service updates in a format that is recognizable and easy to navigate.
These examples represent more than a richer presentation layer. They reduce the distance between receiving a message and taking action. They can also give consumers greater confidence in the identity of the sender—an increasingly important consideration as businesses look for more trusted ways to engage their customers.
For operators, this creates an opportunity to remain central to the business messaging value chain as it grows. The objective is not simply to support a new messaging format. It is to help establish a trusted, scalable channel capable of generating sustained enterprise demand.
Evolution Does Not Mean Replacement
The growth of RCS has also created a misconception that can affect operator investment decisions: if RCS is the future of messaging, upgrading SMS infrastructure may no longer be necessary.
That presents a false choice.
The continued volume of traditional messaging underscores the point. According to CTIA’s 2025 Annual Survey, Americans exchanged nearly 2.2 trillion SMS and MMS messages in 2024—nearly 42 billion more than the previous year. That momentum is also visible in business messaging: Infobip analyzed 628 billion mobile-channel interactions on its platform in 2025—approximately 18% more than in 2024—with SMS still accounting for 62% of traffic.
RCS will expand what mobile messaging can accomplish, but it will not eliminate the need for SMS. Messages must still reach customers when RCS is unavailable, when a device is unsupported or when a subscriber is roaming internationally. Critical and emergency communications—including fraud notifications, outage alerts and travel updates—cannot depend exclusively on the availability of a rich messaging session.
SMS also continues to support less-visible but operationally important network functions, including certain provisioning, activation, registration, and device-management processes. These functions may receive less attention than conversational commerce or rich media, but they remain part of the infrastructure on which mobile services depend.
Maintaining a modern SMS foundation is therefore not an investment in the past. It is an investment in continuity, resilience and the ability to support an evolving messaging environment.
Building the Complete Messaging Roadmap
The strongest operator strategy is not SMS or RCS. It is SMS and RCS.
SMS provides the dependable reach that established mobile messaging as a universal channel. RCS adds the trusted, interactive experiences that can deepen engagement and open new commercial opportunities. Together, they allow operators to meet current communications requirements while preparing for the next phase of business messaging.
The strategic question is no longer whether RCS has the capabilities to change the market. It is whether the industry can make those capabilities broadly available fast enough to change market behavior.
Achieving that scale will require continued operator participation, a clear path from evaluation to deployment and an infrastructure strategy that recognizes the complementary roles of both RCS and SMS. Operators that invest in both will be better positioned to protect service continuity, capture new messaging revenue and remain essential to the way businesses communicate with mobile users.
About Jim Dwyer
Jim Dwyer III is Senior Vice President, Corporate Development at Interop Technologies, where he oversees strategic relationships and channel partnerships and helps guide the company’s product delivery and market roadmap. His wireless experience includes 11 years at Wireless One Network, where he held leadership roles across customer support, IT, billing and roaming before becoming executive vice president. Following the company’s acquisition by AT&T Wireless, Jim led the transition team and continued supporting the integration for another year.
To contribute content, please contact comms@ccamobile.org. (CCA members only.)